Unlocking Equity With a HELOC: Two Ways Your Home Can Fund Your Next Move
Many homeowners are sitting on equity they never use. They think of it as money locked inside their walls, out of reach until they sell. A home equity line of credit (HELOC) can change that. Here are two success stories that show how equity can open the door to a new primary home or an investment property.
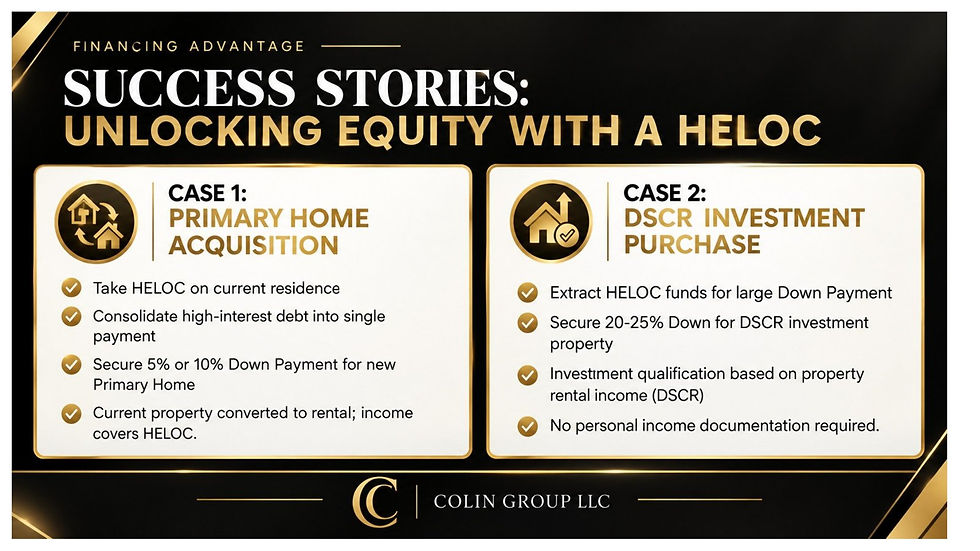
Case 1: Primary home acquisition
The scenario and challenge: A homeowner wanted to move into a new primary home but faced two obstacles: high-interest debt and the need for a down payment.
How it was structured: They took a HELOC on their current residence. With it, they consolidated high-interest debt into a single payment and secured a 5% or 10% down payment for the new primary home. Instead of selling, the current property was converted to a rental, and that rental income covers the HELOC.
The result: A new primary home, a simpler monthly picture with one payment instead of several high-interest debts, and a rental property whose income covers the HELOC.
Case 2: DSCR investment purchase
The scenario and challenge: An investor wanted to buy an investment property. DSCR loans typically call for a large down payment, and qualifying with personal income documentation isn't always the best fit.
How it was structured: The investor extracted HELOC funds for the large down payment, securing 20–25% down for a DSCR investment property. With DSCR, qualification is based on the property's rental income, so no personal income documentation was required.
The result: Equity from an existing home became the down payment on an income-producing property, and the loan was qualified on the property's rental income.
The lesson
Your equity is a tool. Used strategically, a HELOC can help you consolidate debt, keep a property you already own as a rental, and fund the down payment on your next home or investment. Every situation is different. Terms, available equity, and rental income all matter, so the right structure starts with a careful review of your numbers.
Curious how much equity you could put to work? Apply at our online portal or book a consultation at calendly.com/lorenacolin.


Comments